
 1 week ago
59
Inflation is refusing to finish its victory lap. With the Bureau of Labor Statistics set to release August 2026 CPI data on September 11, prediction market platform Kalshi is assigning a 62% probability that year-over-year headline inflation will come in above 3.3%. That contract is currently trading at 62 cents.
The timing matters enormously. The Federal Open Market Committee meets September 15-16, meaning policymakers will have exactly four days to digest the August print before deciding whether to raise rates for the first time since 2023.
What the numbers actually say
Economist consensus, compiled by FactSet, is clustering around a 3.3% year-over-year headline CPI reading for August. That would represent a slight softening from July’s 3.4% figure, which itself marked a deceleration from the mid-2026 peak of 3.5%.
Core CPI, which strips out food and energy, is expected to land around 2.4% year-over-year. July’s core reading was 2.5%.
On a month-over-month basis, forecasters at MUFG Research and FactSet are penciling in headline gains of between 0.3% and 0.4%, with core monthly change expected at 0.2%.
The wildcard is gasoline. Energy prices have been flagged as a meaningful upside risk for August, and a notable jump at the pump could push the headline number toward the higher end of projections or beyond it. The 18% probability currently priced into Kalshi’s contract for CPI exceeding 3.4% reflects exactly that scenario.
Why the Fed is watching so closely
The Federal Reserve has been operating above its 2% inflation target for long enough that patience is wearing thin in some corners of the FOMC. Inflation has drifted down from that 3.5% mid-2026 peak, but the journey from 3.4% to 2% still has meaningful distance to cover.
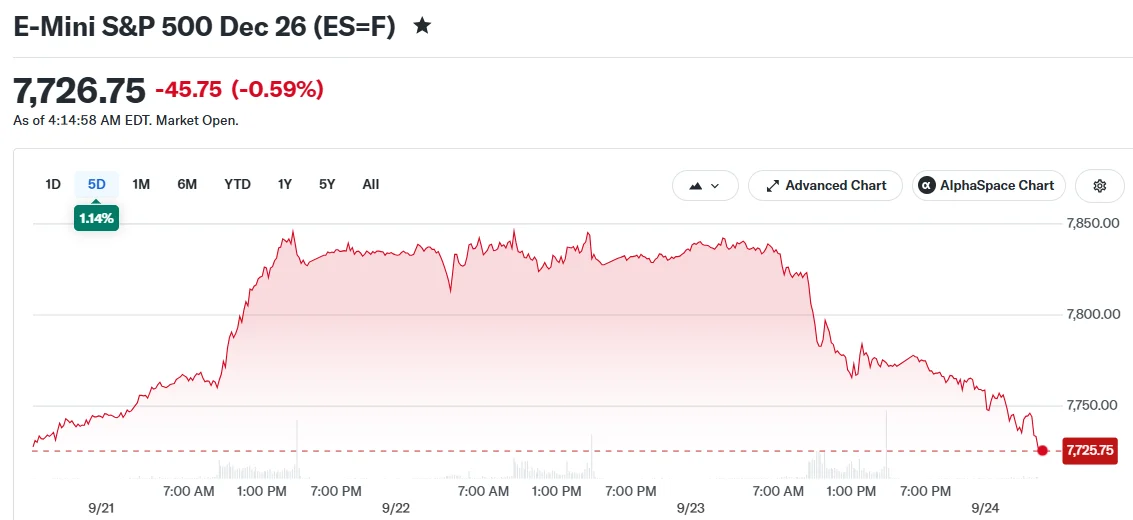
A reading that comes in above consensus, say 3.5% or higher, would reopen a debate many assumed was settled: whether the Fed needs to hike rates one more time. Market pricing for a September rate increase has been hovering between 60% and 70%.
Rate-sensitive sectors are the most exposed to whatever comes out on September 11. Real estate and utilities tend to sell off when rate hike expectations climb.
Reading the prediction market signal
The gap between the 62% probability for above 3.3% and the 18% probability for above 3.4% is revealing. It suggests the market’s modal expectation is a print right in that 3.3% to 3.4% range: hot enough to keep the Fed uncomfortable, but not dramatic enough to force an immediate policy response.
The broader inflation arc since the mid-2026 peak does offer some reassurance. Three consecutive months of deceleration, from 3.5% to 3.4% to an expected 3.3%, is directionally correct even if the pace feels glacial relative to the Fed’s 2% target.
Disclosure: This article was edited by Editorial Team. For more information on how we create and review content, see our Editorial Policy.



 English (US) ·